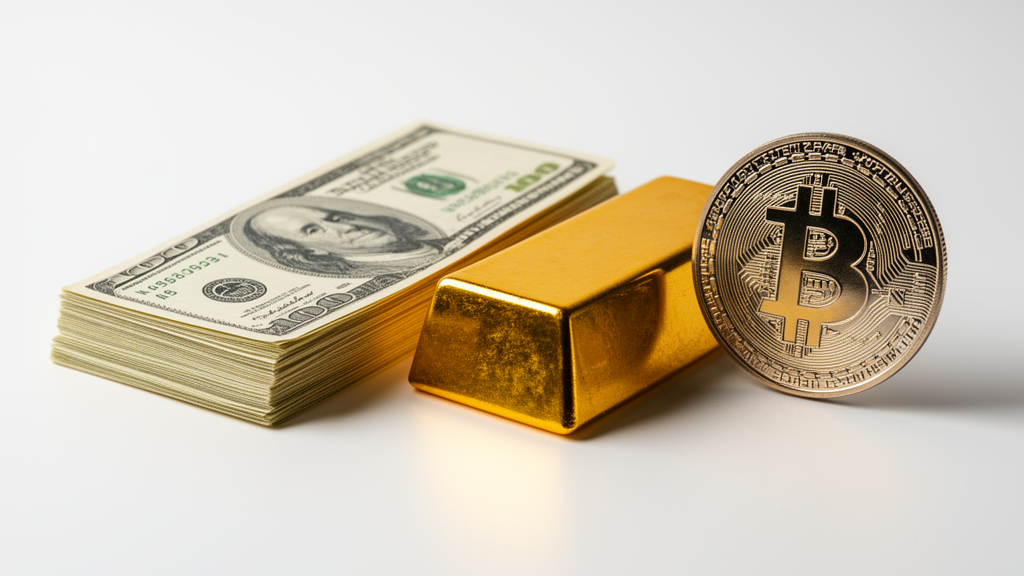
A new econometric investigation analyzing daily financial and global risk indicators from 2013 to 2024 demonstrates that the United States dollar and gold serve as resilient safe-haven assets against compounding systemic tail risks, whereas bitcoin fails to act as an effective hedge and functions primarily as a portfolio diversifier. The empirical study, conducted by researchers Salma Tarchella and Abderrazak Dhaoui, evaluated how the three defensive assets responded to four distinct sources of systemic shocks: stock market volatility measured by the CBOE Volatility Index, crude oil uncertainty captured by the Oil Volatility Index, geopolitical stress measured by the Geopolitical Risk Index, and media-tracked climate concerns captured by the Climate Risk Index. Across multi-scale market conditions and holding horizons, the US dollar emerged as the foremost defensive buffer, followed closely by gold, showing that traditional fiat and commodity anchors retain superior hedging rigidity compared to contemporary digital assets.
The research paper addresses a longstanding empirical challenge in finance by questioning whether safe-haven asset properties remain stable across different categories of global distress or whether they depend intrinsically on investment horizons and the specific structural origin of risk. Traditional empirical literature frequently evaluates asset shelters under the assumption that financial panics represent homogeneous stress events, predominantly relying on stock market volatility benchmarks like the S&P 500 implied volatility. However, systemic disturbances increasingly originate outside conventional equity markets, including international military conflicts, structural energy disruptions, and physical and transition risks associated with environmental instability. To examine whether capital protection varies under such disparate market shocks, the authors formulated an analytical question testing the degree to which gold, the US dollar, and bitcoin exhibit hedge, safe-haven, or diversification capabilities across extreme investment frequencies and localized market states.
To provide theoretical grounding for empirical differences across asset classes, the researchers synthesized the flight-to-quality and flight-to-liquidity hypotheses, the fractal market hypothesis, and the emerging concept of polycrisis risk spillovers. Under flight-to-quality mechanics, acute market panics prompt capital to rotate rapidly away from high-beta, informationally sensitive assets toward instruments possessing deep market liquidity, negligible default probabilities, or intrinsic value. Furthermore, the fractal market hypothesis posits that financial stability is maintained through the participation of heterogeneous market actors operating across vastly divergent time frames, from intraday liquidity providers to multi-year institutional asset managers. By recognizing that non-financial shocks such as climate catastrophes or geopolitical warfare introduce long-wave structural transformations in real economic activity rather than short-lived liquidity squeezes, the study models how asset defensive behavior emerges or decays across different operational scales.
The methodological framework developed by the investigators combines Maximal Overlap Discrete Wavelet Transform with quantile regression and quantile-on-quantile regression. Using the Daubechies least asymmetric filter of length seven, return series were decomposed into seven distinct frequency scales spanning detailed short-term oscillations of two to four days up to long-term cyclical movements of 128 to 256 days. Conventional econometric approaches, such as ordinary least squares, capture only average tendencies and often fail to produce statistically meaningful relationships because financial time series exhibit heavy tails, serial correlation, and non-normal distributional asymmetry. By applying quantile regression, the authors estimated marginal dependence across nine specific quantiles ranging from extreme bearish conditions at the 0.05 mark to bullish conditions at 0.95. The subsequent quantile-on-quantile regressions extended this formulation by simultaneously tracking how localized quantiles of risk indices interacted with corresponding quantiles of asset returns.
The empirical dataset utilized in the study compiled daily trading observations spanning January 2, 2013, to January 19, 2024, gathering asset return benchmarks from Investing.com alongside risk metrics sourced from the Federal Reserve Bank of St. Louis and academic risk indices. Descriptive statistical tests confirmed the presence of marked non-normality across all examined series, with the US dollar recording the lowest overall price volatility, followed by gold. Skewness metrics revealed negative left-skewed distributions for gold and the US dollar, while the remaining variables exhibited positive right-skewness. Kurtosis values substantially exceeded Gaussian thresholds for nearly all indicators, while Shapiro-Wilk, ARCH-LM, and Ljung-Box tests established severe non-normality, conditional heteroskedasticity, and serial dependence. Crucially, Brock-Dechert-Scheinkman tests rejected the null hypothesis of independent and identically distributed returns, demonstrating nonlinear dependence across embedding dimensions and reinforcing the necessity of a wavelet-quantile framework.
Empirical estimations from the Wavelet-Quantile Regression model established stark contrasts between traditional assets and digital alternatives, particularly across distinct holding periods. For gold, exposure to equity market volatility reflected by the VIX yielded a statistically significant positive relationship at short-term horizons in upper return quantiles, confirming its classic role as an immediate shock absorber during severe financial crises. Over long-term horizons, however, this dependence turned negative at the highest quantile, indicating that gold’s capacity to hedge stock market volatility diminishes over extended holding periods as volatility reverts toward historical means. Conversely, the US dollar displayed an opposite temporal trajectory against financial volatility: while its short-term association with the VIX was negative at the 0.05 quantile, long-term relationships became strongly positive in upper quantiles, proving that the currency delivers greater structural hedging efficacy over prolonged horizons.
The analysis revealed nuanced patterns when assessing asset sensitivity to energy shocks and geopolitical turmoil. Gold reacted positively and significantly to oil volatility across both short-term bearish conditions and long-term bullish environments, reinforcing its function as an effective defensive buffer against commodity market instability. Against geopolitical risk, gold exhibited a positive short-term response during bullish market conditions but suffered negative impacts during bearish regimes, demonstrating that its short-term safe-haven protection against political conflict is strictly regime-dependent. Over longer horizons, gold demonstrated a sustained positive relationship with geopolitical risk across market states. In contrast, the US dollar functioned as an immediate geopolitical hedge, displaying strong positive dependence at upper quantiles in the short term, while its long-term defensive power against geopolitical disruptions experienced noticeable decay.
In evaluating climate-related tail risks, the empirical findings documented a unique role for the US dollar compared to gold and digital assets. Gold exhibited statistically insignificant movements in response to climate risk indices over short-term periods, shifting toward positive but statistically insignificant dependence over long-term cycles, which indicates that physical and transition climate concerns act as gradual, structural disruptions rather than sudden pricing catalysts for bullion. Meanwhile, the US dollar exhibited pervasive, highly resilient safe-haven and hedging properties against climate shocks across both short- and long-term horizons, maintaining dominant positive dependencies across return quantiles. The researchers noted that because climate disruptions primarily damage energy-intensive production sectors and physical infrastructure, their immediate impact on the broader US economic architecture remains muted, thereby sustaining institutional confidence and driving global capital into dollar-denominated reserves.
Throughout the empirical evaluations, bitcoin failed to exhibit the protective characteristics required of a bona fide safe-haven asset or hedge, showing erratic and predominantly non-defensive behavior across risk factors. When subjected to financial volatility via the VIX, bitcoin displayed statistically significant negative dependencies during normal short-term market states, indicating that its market price depreciates rather than appreciates when financial turmoil accelerates. Although bitcoin demonstrated weak positive responses to geopolitical risk and climate stress in localized extreme tails, its overall sensitivity remained largely homogeneous across underlying risk sources. Instead of mirroring the counter-cyclical stability of traditional monetary anchors, the digital cryptocurrency behaved as a high-beta, speculative asset whose weak and unstable co-movements align with the classical definition of a portfolio diversifier rather than an insurance hedge.
To interpret the mechanisms underpinning the US dollar’s strong safe-haven rank, the authors emphasized the necessity of distinguishing pure portfolio hedging decisions from structural flight-to-liquidity dynamics. During severe international financial distress, foreign institutions encounter acute dollar shortages, driving up spot exchange rates as global counterparties scramble for liquidity to settle debt obligations. By decomposing the series into distinct wavelet frequencies and examining heterogeneous risk categories, the study demonstrated that while high-frequency co-movements reflect short-term liquidity demands and central bank swap operations, lower-frequency persistence reflects genuine long-term capital preservation motives. The asymmetry of dollar appreciation across diverse risk drivers—such as its pronounced long-term hedging against climate and energy shocks—confirms that its safe-haven performance does not stem merely from uniform crisis-induced settlement rushes.
The authors concluded by noting essential methodological and practical limitations inherent in their investigation, highlighting critical pathways for future econometric inquiry. While the core sample spanned over a decade of trading through January 2024, the climate risk index was constrained by external data availability and terminated on August 31, 2022, preventing uniform cross-variable coefficient comparisons across the terminal sample months. Furthermore, the empirical framework evaluated safe-haven status based on statistical tail dependence and localized quantile elasticity rather than testing realized out-of-sample portfolio allocations or backtested Sharpe ratios. The researchers noted that subsequent scholarly work could build upon their dynamic multi-horizon framework by assessing the systemic integration of central bank digital currencies and examining safe-haven transmission pathways within emerging market financial architectures.
Subject of Research: Safe-haven resilience of gold, the US dollar, and bitcoin against systemic tail risks across investment horizons
Article Title: Safe-haven resilience of gold, USD, and bitcoin against tail risks: evidence from wavelet-based quantile and quantile-on-quantile regressions
Article References: Tarchella, S., & Dhaoui, A. (2026). Safe-haven resilience of gold, USD, and bitcoin against tail risks: evidence from wavelet-based quantile and quantile-on-quantile regressions. Discover Analytics, 4(1), Article 52. https://doi.org/10.1007/s44257-026-00103-3
Image Credits: AI Generated
DOI: 10.1007/s44257-026-00103-3
Keywords: safe-haven assets, gold, US dollar, bitcoin, systemic tail risks, wavelet analysis, quantile regression, quantile-on-quantile regression, market volatility, VIX index, oil volatility, OVX index, geopolitical risk, climate risk, portfolio diversification, financial econometrics, investment horizons
News Source: Denise Maddox. (November 19, 2026). US Dollar and Gold Show Tail-Risk Resilience While Bitcoin Functions as Diversifier. Scienmag.